Consulting

Treasury and ALM consulting for financial institutions

Practical advice on liquidity, funding, interest rate risk and the balance sheet, from people who have run a bank’s treasury. We help banks and other financial institutions design, implement and streamline their treasury and asset & liability management (ALM).

What we work on

Where we help

From measuring risk to steering the balance sheet, and the processes and systems behind both.

  • Interest rate risk in the banking book

    Measuring and steering IRRBB: repricing gaps, EVE and NII sensitivities, scenario design, behavioral assumptions for deposits, and the hedging strategy.

  • Liquidity and funding

    Liquidity risk measurement and stress testing, LCR and NSFR, contingency funding plans, and a funding strategy that balances cost and resilience.

  • Funds transfer pricing

    FTP frameworks that charge and credit liquidity and interest rate risk consistently across business lines, so that pricing and performance reflect them.

  • Hedge accounting and valuation

    IFRS 9 hedge accounting, fair value measurement under IFRS 13, discounting, and the curves the valuations rest on.

  • Balance sheet and capital

    Balance sheet steering, capital efficiency, ALCO reporting and the governance around them, in line with regulatory requirements.

  • Treasury processes and systems

    Target operating models, process design, the selection and introduction of treasury and ALM systems, data and regulatory reporting.

How we work

Practitioners, not slide decks

  • Senior and hands-on

    The people you meet are the people who do the work, with treasury experience from the inside of a bank.

  • From analysis to implementation

    We do not stop at recommendations: we help put models, processes and reports into practice.

  • Built for your team

    Models and reports your own staff can run, understand, and explain to auditors and regulators.

  • Finance and technology together

    We speak treasury and IT alike, and we build financial software ourselves.

The data behind the models

It starts with the curves

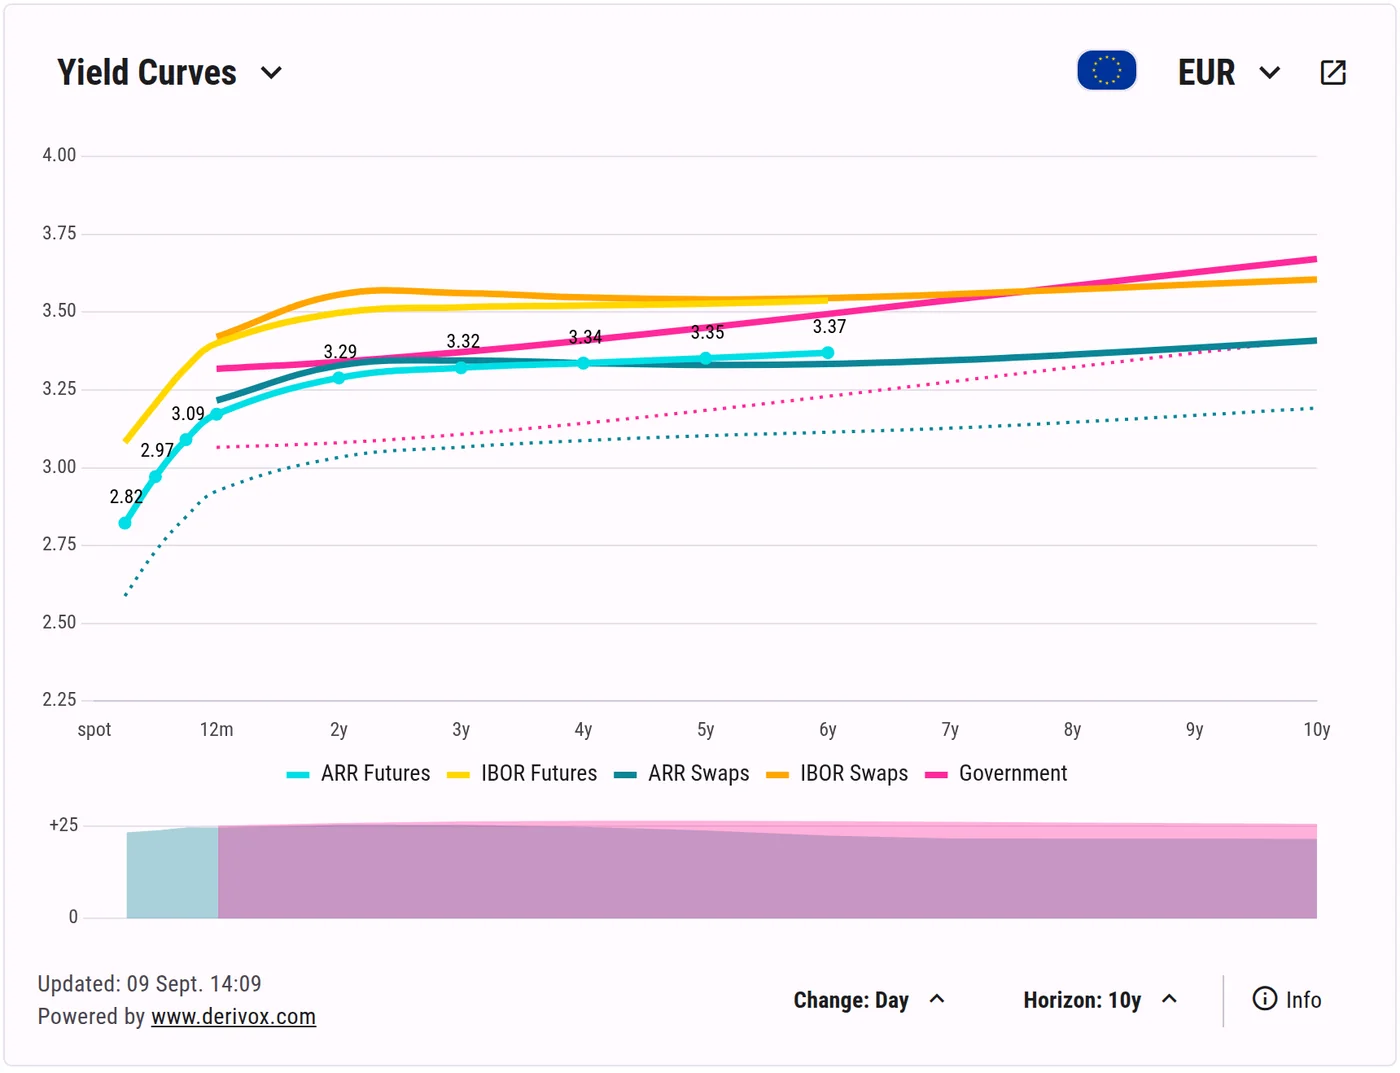
IRRBB scenarios, transfer pricing curves, discounting and hedge effectiveness tests all start with reliable interest rate curves. That is why we built Derivox: daily end-of-day curves with discount factors and forward rates for 13 currencies, delivered by API, Excel add-in or widget at a flat license fee.

The Derivox widget showing EUR yield curves
The Derivox widget with EUR yield curves

Who you will work with

Your counterpart

Portrait of Jean-François Alarie

Jean-François Alarie

Treasury, ALM and product development

Jean-François Alarie brings together finance and technology. As Group Treasurer at Bank Julius Baer, he specialized in treasury management, financial risk and asset & liability management. His background also includes interest rate derivatives trading and balance sheet regulatory reporting.

On the technical side, he has developed IT solutions for banks, financial brokers, hedge funds and commodity traders. At Ensium he develops the company’s products, Zendrea and Derivox, and advises financial institutions on treasury and ALM.

Have a treasury or ALM question?

Tell us what you are working on. We will get back to you personally.

Also: IT project management